What CRP Enrollment and Farmland Assessment Do to Your Property Tax Bill When You Buy Recreational Land in Illinois
The Property Tax Question Every Recreational Land Buyer Should Ask Before Closing
The annual property tax bill on Illinois recreational land is not fixed at purchase — it is a function of how the county assessor has classified the land, what Productivity Index is assigned to the soil, and whether the buyer's intended use changes the basis for that classification. A buyer who assumes the current owner's property tax bill will be their property tax bill after closing is making an assumption that may or may not be true, depending on how the current assessment was established and whether the new owner's use of the property matches the use that produced the current classification.
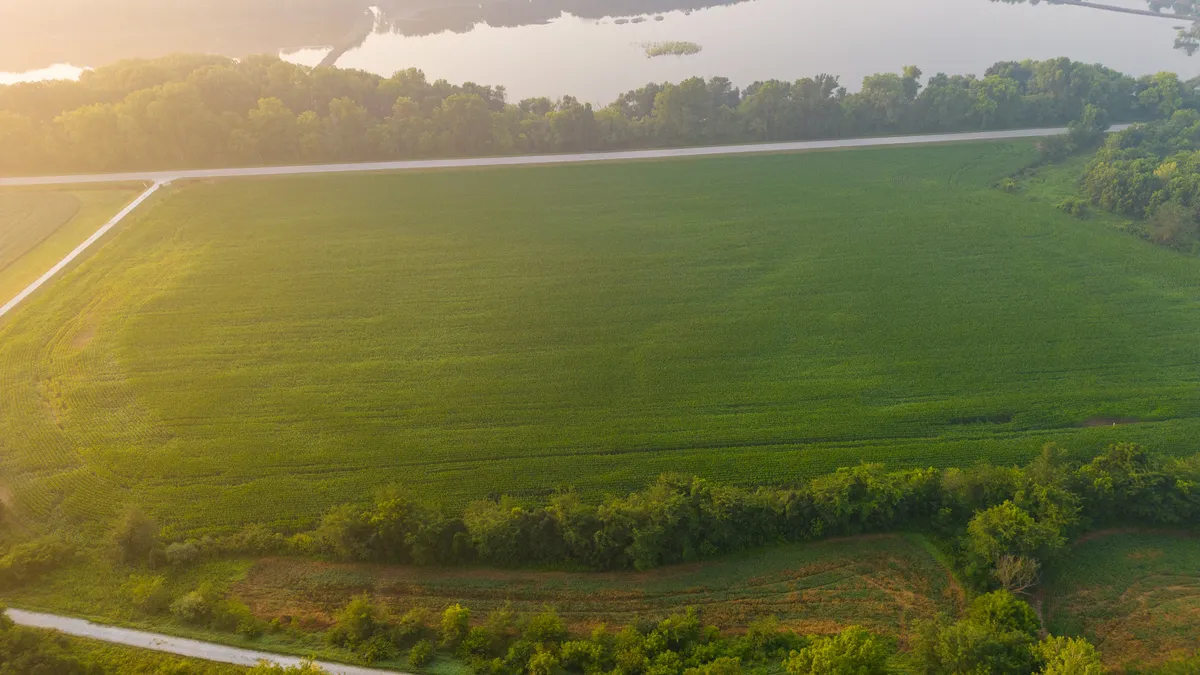
In Brown and Schuyler Counties — the western Illinois bluff-country counties where I see the most recreational land transactions — the property tax picture on a typical hunting tract involves several layers. The tillable acres within the tract are assessed under the agricultural use framework based on their PI. The timber and rough acres may be assessed as agricultural (if the county assessor and the state's classification framework treat them as such) or as a non-agricultural category that produces a different assessment rate. The CRP-enrolled acres carry their own classification question. And any cabin, improvements, or structures on the property are assessed separately as real estate improvements.
How Agricultural Assessment Changes the Tax Bill on Recreational Ground
Illinois property tax on agricultural land is calculated on the equalized assessed value per acre published by the Illinois Department of Revenue, which is derived from the soil's Productivity Index and the statewide farmland assessment formula. For a typical piece of bluff-country recreational ground in Brown County with PI values in the 70 to 95 range for the agricultural acres, the equalized assessed value per acre is a fraction of what the market value of that same acre is for deer hunting — sometimes as low as 10 to 15 cents on the dollar of market value.
The result is a property tax bill on the agricultural acres that is meaningfully lower than a market-value assessment of the same ground would produce. A 100-acre Brown County tract with 60 agricultural acres at PI 85 and 40 acres of timber might carry a total property tax bill of $800 to $1,200 per year if the agricultural classification is correctly applied to the qualifying acres. The same tract assessed at a fair market recreational value — which the county has no reason to do if the agricultural classification applies — would produce a dramatically higher bill based on the $3,000 to $4,000 per-acre market value of that hunting ground.
A buyer who is acquiring recreational ground in Brown or Schuyler County should request the current property tax bill and the assessment breakdown — how many acres are classified as agricultural, how many as timber or rough, and whether any acres carry a non-agricultural classification. If the agricultural classification is not fully applied to qualifying acres, the buyer may have an opportunity to request reclassification through the county assessor before or after closing.
CRP Enrollment — What It Adds in Income and What It Requires in Obligations
A CRP-enrolled tract in Brown or Schuyler County carries a USDA contract that pays the landowner an annual rental rate — typically $75 to $120 per enrolled acre per year for grass or native cover practices in western Illinois, varying by practice and county rental rates. That annual payment partially offsets the carrying cost of the property and is one of the factors that makes CRP-enrolled recreational ground attractive to buyers who want hunting access and some income from the land.
The CRP contract also restricts land use for the duration of the enrollment period. The enrolled acres must be maintained in the specified practice — whether native grass, food plot cover, or wildlife habitat planting — and the landowner cannot plow, clear, or otherwise disturb the enrolled cover without violating the contract and triggering repayment obligations. For a buyer who wants to reconfigure the property — move a food plot from one location to another, clear a section of overgrown grass for a deer stand complex, or install a pond — the CRP contract restrictions are directly relevant to what can be done on the enrolled acres during the contract term.
Request the full CRP contract documentation before closing: the contract number, the enrolled acres and practices, the annual payment amount, the contract expiration date, and any compliance history. Verify the contract expiration against the buyer's plans for the property. A contract that expires in two years leaves the buyer a short wait before they have full flexibility on the enrolled acres. A contract with eight years remaining locks the enrolled practices in place for most of a decade.
What Actual Tax Bills Look Like on Brown and Schuyler County Recreational Ground
The pattern I see on Brown and Schuyler County recreational tracts is that well-classified properties — where the agricultural and timber acres are correctly assigned to the agricultural assessment framework — carry total property tax bills in the range of $4 to $8 per acre per year on the full tract. A 120-acre tract might pay $600 to $960 in total property taxes annually. That is a carrying cost that the annual CRP payment on the enrolled acres can meaningfully offset — a 60-acre CRP practice paying $90 per acre per year generates $5,400 annually, which more than covers the full property tax bill on the tract.
The properties that are over-assessed — where the county has applied a non-agricultural classification to acres that qualify for agricultural assessment — carry higher bills that can sometimes be reduced through a reclassification request or a Board of Review appeal. I addressed the specifics of that process in a previous article. The starting point is always the current assessment breakdown — knowing what classification each parcel portion is currently carrying before deciding whether any action is warranted.
A buyer who runs the full carrying cost calculation before closing — property taxes as currently assessed, estimated mortgage payment if financed, CRP income as documented in the existing contract — has a complete picture of what the property costs to hold on an annual basis. That calculation, compared against what the buyer values the hunting access at, is the arithmetic that determines whether the acquisition makes financial sense. The purchase price is only the beginning of that calculation.
Jared Williams is the Managing Broker and owner of Archer Realty & Auction LLC. He serves on the Menard County Board of Review and specializes in recreational and agricultural land across central and western Illinois. Start the conversation at archerrealty.net.